Norton Park Sales Policy 2026 | Payment Plans & Discounts
- Home
- Norton Park Sales Policy 2026 | Payment Plans & Discounts
Description
Contact Us for Norton Park Sales Information
Interested in Norton Park apartments, duplex units, or the latest sales policy? Contact us for updated pricing, floor plans, available units, payment options, and project information.
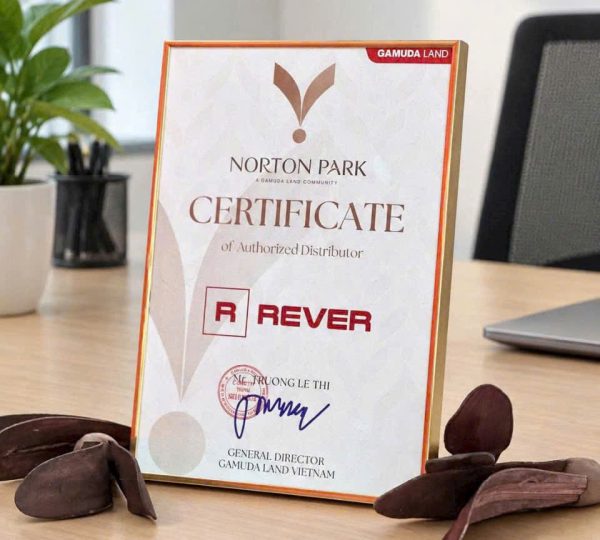
We provide property consultation through Rever, an F1 sales agency for Norton Park, helping buyers explore suitable options and understand the purchasing process.
Contact us today to request the latest information and arrange a consultation.
Phone / WhatsApp / Zalo: +84 945 133 789
Norton Park Sales Policy 2026: Payment Plans, Discounts and Buyer Guide
Understanding the Norton Park sales policy is an important step for buyers considering an apartment at Norton Park by Gamuda Land in Ho Chi Minh City. Beyond the apartment price, the payment schedule, available incentives and financing conditions can significantly affect a buyer's financial planning.
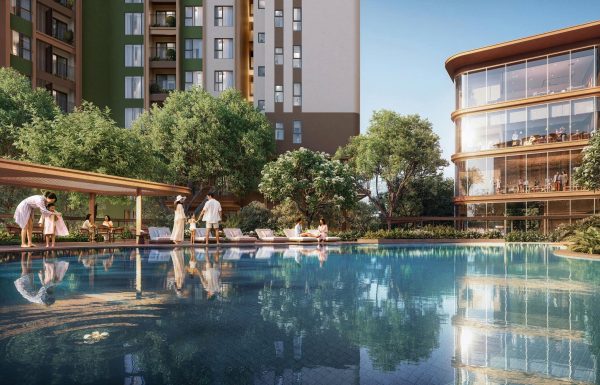
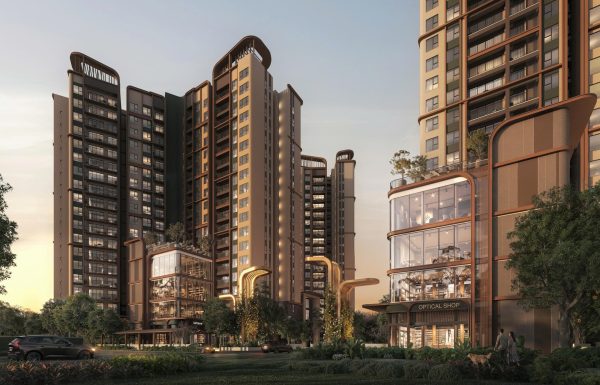
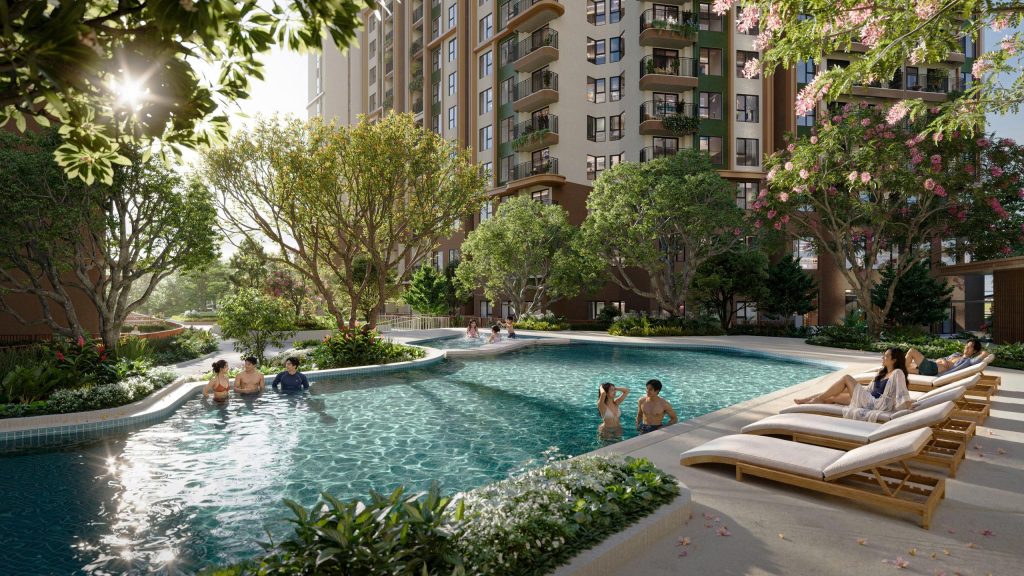
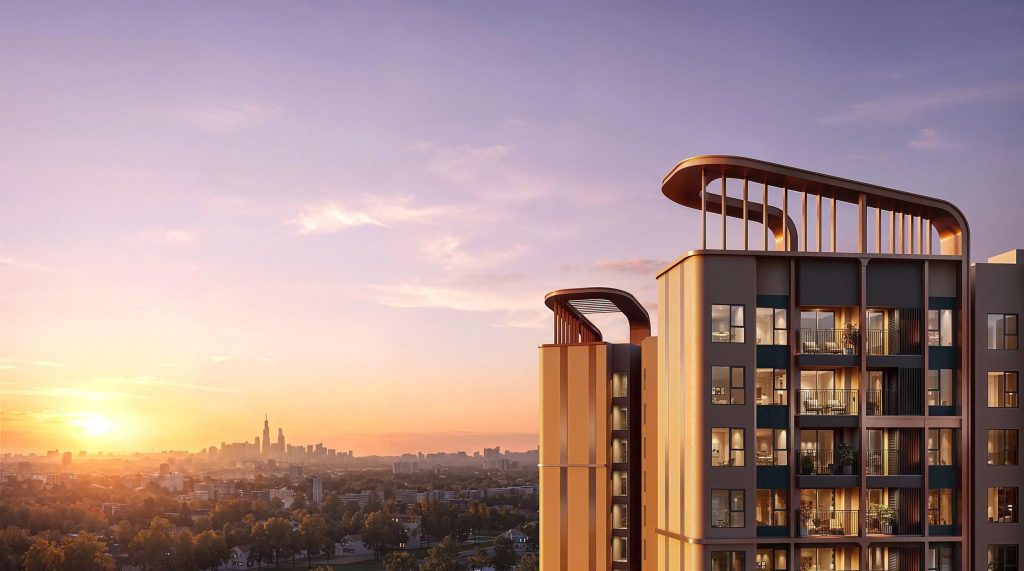
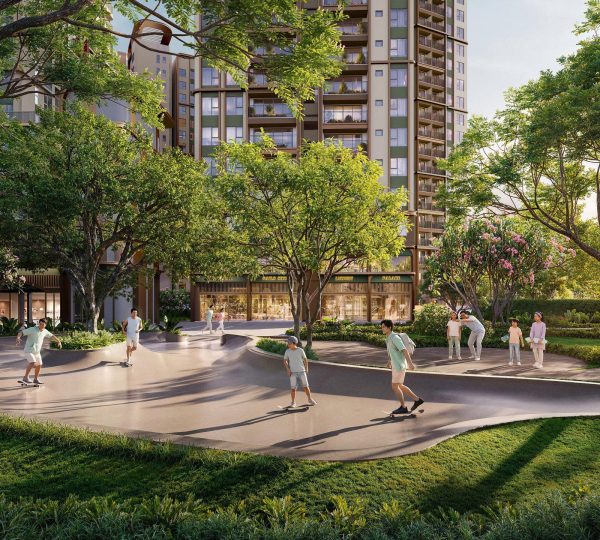
Norton Park is positioned around a contemporary lifestyle that combines green spaces, modern architecture and convenient urban living. For prospective homeowners and property investors, understanding the sales policy can help determine whether a particular apartment fits their budget and long-term plans.
This guide explains the main payment options reported for Norton Park, the potential benefits of each approach and the essential details buyers should verify before making a purchase.
Important: Sales policies, discounts, payment dates and bank-support conditions may change between sales phases. The information below is for reference and should be confirmed against the latest official documents from the developer or its authorized sales team.
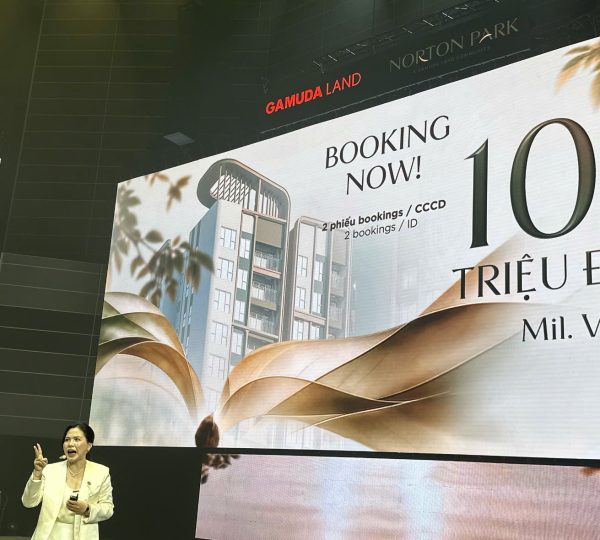
1. Overview of Norton Park Sales Policy
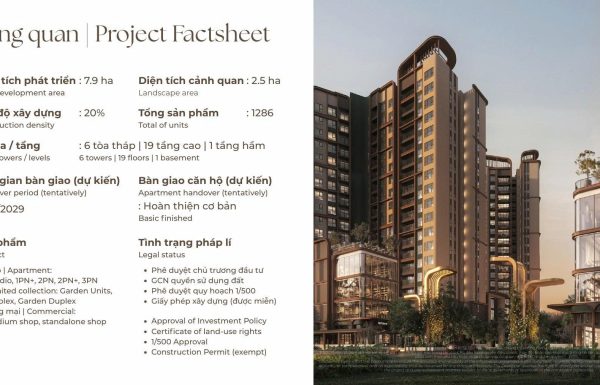
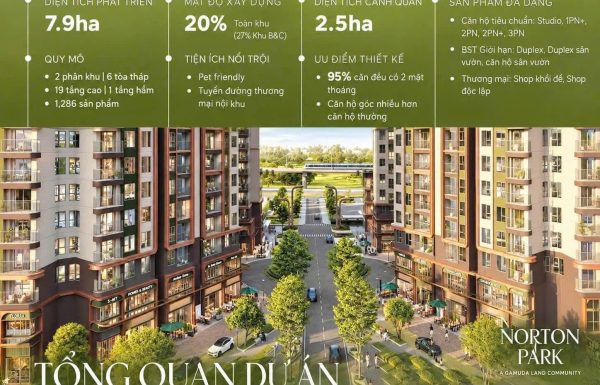
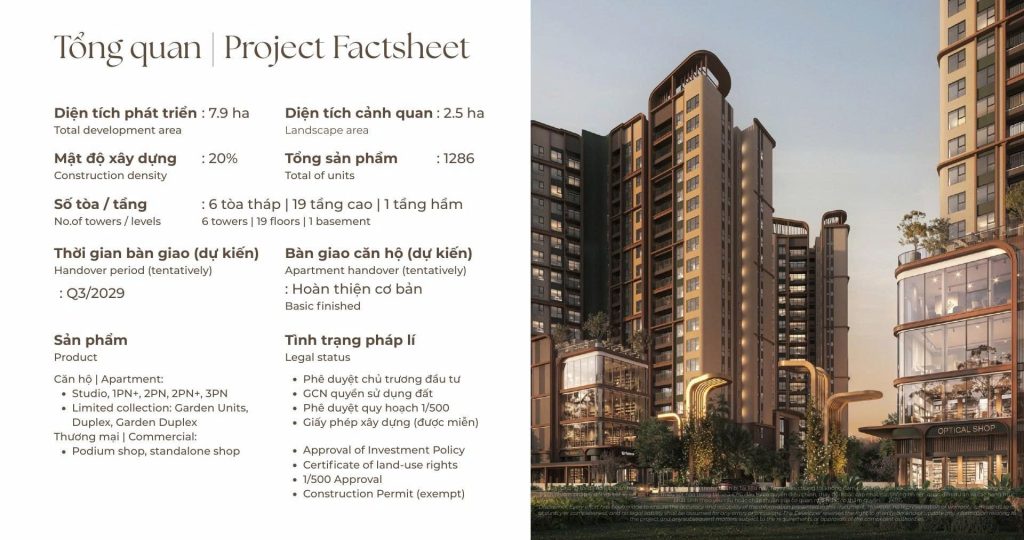
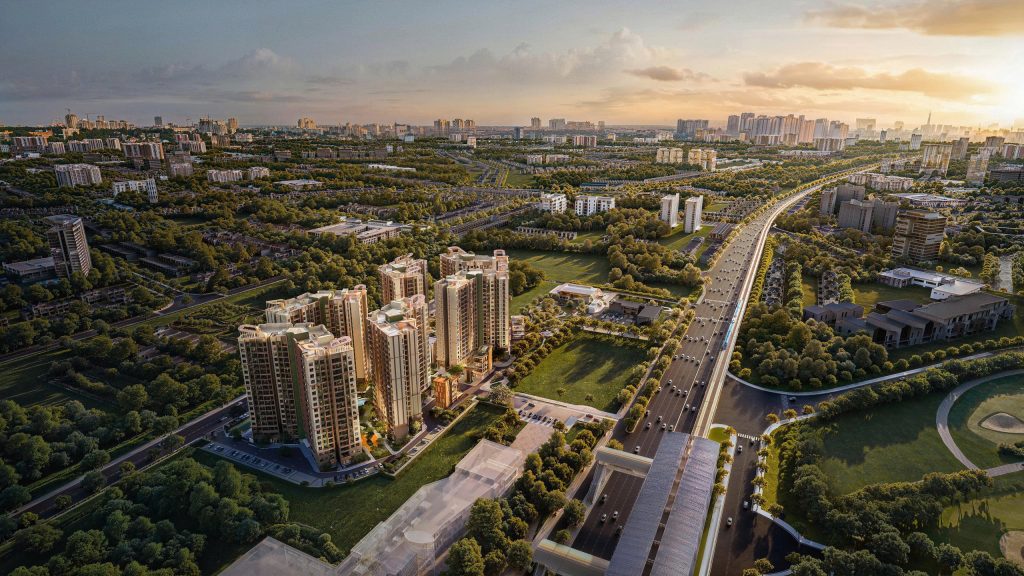
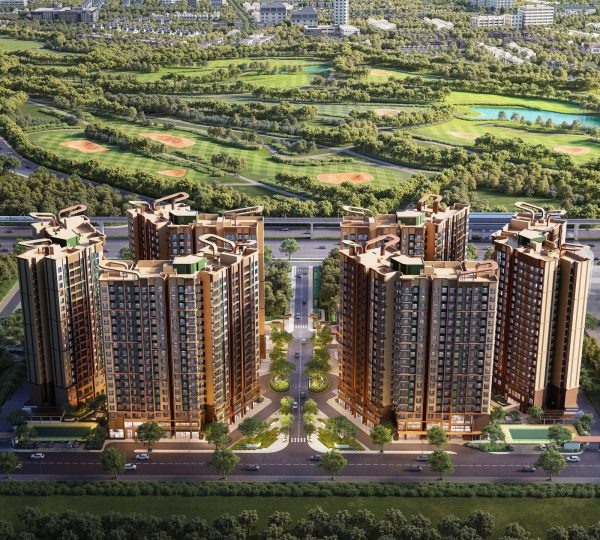
Norton Park is a residential development by Gamuda Land located along Binh Duong Boulevard, in the Thuan Giao area of Ho Chi Minh City.
The development offers different apartment configurations and commercial products, giving buyers options based on their household requirements, preferred layout and financial capacity.
When reviewing the Norton Park sales policy, buyers should pay attention to five main factors:
- Initial payment: The amount required at each contractual milestone.
- Payment schedule: Whether payments are spread over several months or concentrated earlier.
- Discounts and incentives: The conditions for qualifying for a particular offer.
- Bank financing: Loan eligibility, disbursement conditions and interest-rate support, if applicable.
- Handover and final payments: The expected handover date and the amounts payable at handover or when completing ownership documentation.
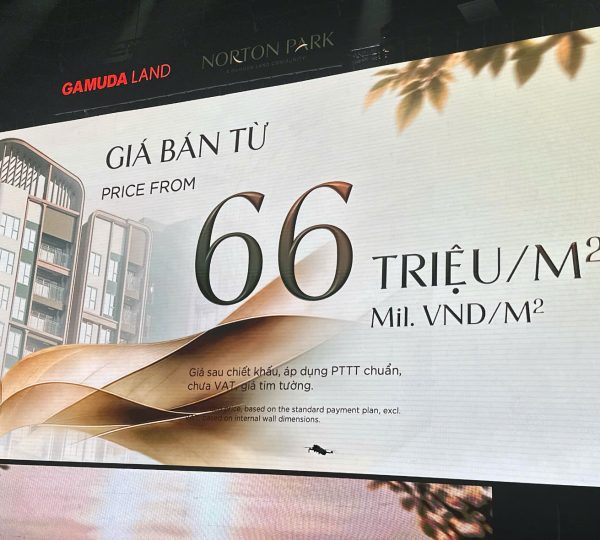
According to publicly available project information in October 2026, the indicative apartment price was around VND 66 million per square metre before VAT. This is a reference figure rather than a guaranteed price for every unit. The final price depends on the specific apartment, its area, floor, position and applicable sales policy.
2. Norton Park Payment Plans
Publicly available Norton Park sales information describes several payment approaches, including a standard payment plan, a faster payment plan and a bank-supported option.
The following is a general comparison of the reported options. Buyers should request the applicable payment schedule for their selected unit before making a financial commitment.
Standard Payment Plan
The standard payment option is designed for buyers who prefer to distribute payments across multiple milestones rather than settle a large proportion of the apartment price early.
An indicative schedule published for October 2026 describes an initial payment milestone of 15%, followed by smaller instalments at intervals of approximately three months. Later payments are linked to subsequent milestones, including handover and ownership documentation.
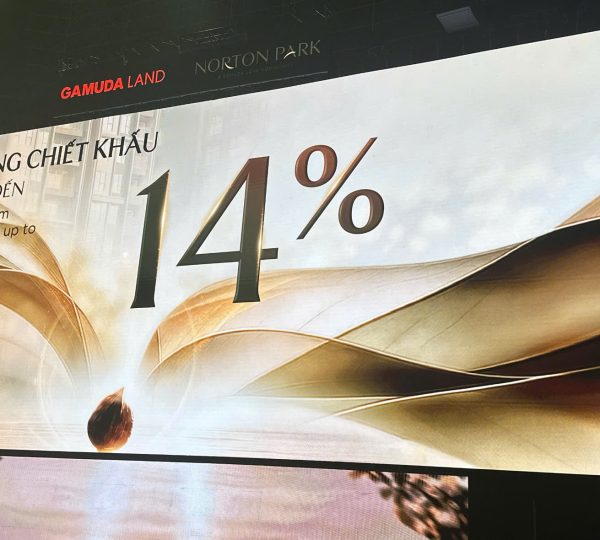
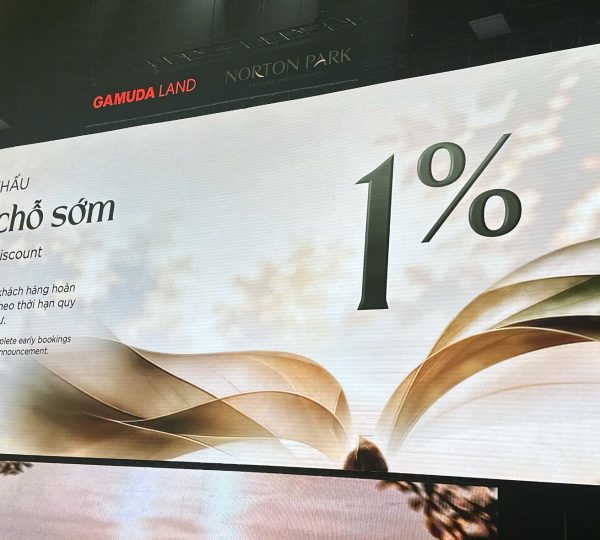
A reported discount of 5% is associated with this particular standard-payment schedule. Eligibility and the calculation basis must be confirmed in the current official policy.
This option may suit buyers who want a structured payment plan and have sufficient income or reserves to meet each instalment when due.
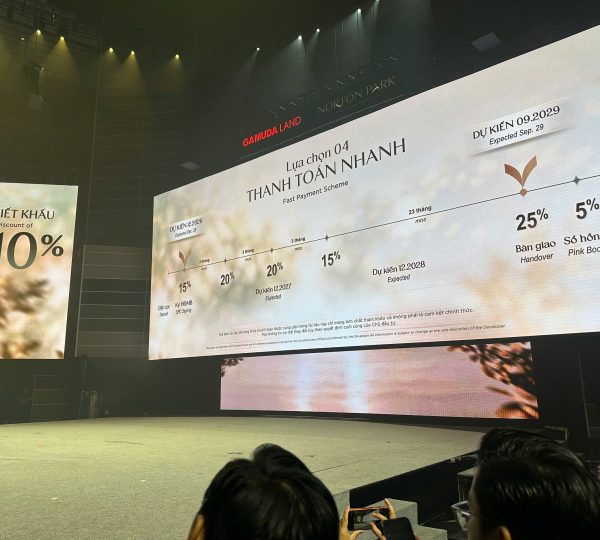
Faster Payment Plan
A faster payment option may appeal to buyers who have a larger amount of available capital and prefer to settle a greater proportion of the apartment price earlier.
An October 2026 reference schedule lists a reported discount of 10% for this option. However, the benefit should be evaluated alongside the amount and timing of each payment.
Before choosing this plan, buyers should confirm:
- The exact payment percentages and due dates.
- The deadline for qualifying for the discount.
- Whether the discount applies to the full eligible apartment price or only a specified component.
- Any conditions that could affect the incentive.
A larger discount does not automatically make a payment plan the best choice. Buyers should also consider liquidity, other financial commitments and the opportunity cost of paying earlier.
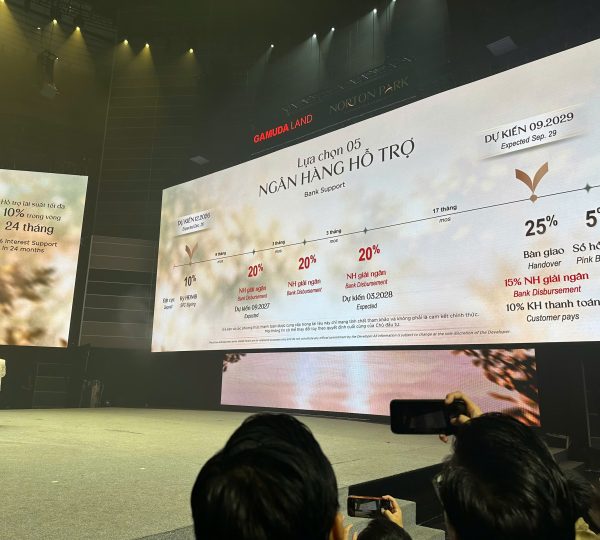
Bank-Supported Payment Option
For buyers who intend to use a mortgage, the bank-supported option may provide a way to structure payments through an approved financing arrangement.
Public project information has reported interest-rate support of up to 10% for 24 months under a particular bank-supported option. This figure should not be interpreted as an unconditional interest-free period or a guaranteed loan approval.
Buyers should ask the participating bank and sales team to confirm the applicable loan-to-value ratio, eligible borrowers, disbursement milestones, interest-support period, repayment obligations and what happens when the support period ends.
A bank-supported plan may be worth considering for buyers who want to preserve some cash reserves, provided the future repayments remain affordable.
3. Norton Park Sales Policy Comparison
| Payment option | Reported benefit | Key consideration |
|---|---|---|
| Standard payment | Reported 5% discount under one published schedule | Plan cash flow around each instalment |
| Faster payment | Reported 10% discount under one published schedule | Requires more capital earlier |
| Bank-supported option | Reported interest support of up to 10% for 24 months | Verify eligibility and all financing terms |
These figures are drawn from publicly available reference information and may not represent every unit or current sales phase. Buyers should obtain the dated policy sheet and written confirmation of the terms applicable to their purchase.
4. How to Choose the Right Norton Park Payment Plan
The best payment plan depends on the buyer's financial position rather than the headline discount alone.
For buyers purchasing a home
Buyers planning to live at Norton Park should start with a realistic household budget. Include the initial payment, scheduled instalments, taxes and fees where applicable, furnishing costs and a reserve for unexpected expenses.
The standard payment option may be worth comparing if predictable instalments are more important than obtaining the largest advertised discount.
For property investors
Investors should compare the total acquisition cost, expected holding period and planned exit strategy. A faster payment plan may offer an incentive, but paying earlier also reduces the cash available for other investments or unexpected expenses.
Do not base a purchase decision solely on an assumed future selling price or rental income. Any projected return should be calculated using realistic costs and clearly stated assumptions.
For buyers using bank financing
Before selecting a bank-supported plan, request a loan illustration that shows the amount borrowed, interest-rate assumptions, monthly repayments during and after any support period, applicable fees and total repayment obligations.
The affordability assessment should remain workable even if interest rates, income or personal circumstances change.
5. Additional Costs Buyers Should Check
The apartment price is only one part of the total purchase cost. Before signing, ask for a written breakdown of any applicable:
- Value-added tax (VAT).
- Maintenance fund contribution.
- Registration fees and other ownership-related costs.
- Bank appraisal, loan arrangement or insurance costs, where applicable.
- Interior furnishing and moving expenses.
- Management fees and other charges after handover.
The amount and timing of each cost depend on the contract, applicable law and the developer's current documentation. Do not assume that every cost is included in the advertised price.
6. Norton Park Handover Timeline
Public project information available in October 2026 indicates an expected handover around September 2029. This is a projected milestone, not a guarantee of the actual handover date.
Buyers should check the expected handover date and any provisions for delays in the sale and purchase agreement. They should also confirm the payment obligations linked to handover and the process for completing ownership documentation.
The signed contract and applicable official documents should take precedence over promotional material or an indicative payment table.
7. Documents to Review Before Booking
Before paying a deposit or signing an agreement, prospective buyers should request and review the relevant documentation.
- The latest official price list for the selected apartment.
- The current sales policy and full payment schedule.
- Written terms for discounts, promotions and eligibility.
- The draft sale and purchase agreement and its payment provisions.
- Relevant project legal documents and confirmation of the project's eligibility for the proposed transaction.
- Bank financing terms, if a mortgage or interest support is involved.
- The apartment's area, floor, orientation, handover specifications and other contractual details.
Buyers should also confirm who is authorized to receive payments and follow the payment instructions stated in the appropriate contractual documents.
8. Is Norton Park Worth Considering?
Norton Park may be worth exploring for buyers seeking an apartment in the Thuan Giao area, particularly those comparing modern residential developments, green-space concepts and access to employment and urban services.
The sales policy is one part of the decision. Buyers should evaluate the location, apartment layout, total acquisition cost, project documentation, handover timeline and their own financial capacity together.
For investors, it is also important to distinguish between the project's positioning and a verified investment outcome. Future capital appreciation and rental demand are not guaranteed.
Frequently Asked Questions About Norton Park Sales Policy
What is the Norton Park sales policy?
The Norton Park sales policy refers to the payment schedules, discounts, financing support and other purchase conditions applicable to a particular sales phase and apartment.
What payment options are available at Norton Park?
Publicly available information in October 2026 describes standard, faster-payment and bank-supported options. Buyers should confirm which options are currently available for their selected unit.
Does Norton Park offer discounts?
Reference information has reported discounts associated with certain payment methods. The amount, eligibility requirements and validity period should be confirmed in writing before purchase.
Does Norton Park provide bank interest-rate support?
A published reference has described interest-rate support of up to 10% for 24 months under a bank-supported option. Actual benefits depend on the applicable policy and financing agreement.
When is Norton Park expected to be handed over?
Public project information indicates an expected handover around September 2029. Buyers should verify the date and contractual provisions in the latest official documents.
Where can I get the latest Norton Park price list and payment schedule?
Contact the developer or its authorized sales team to request the latest dated price list, payment schedule and applicable sales policy. Confirm the details for the exact apartment before making a booking or payment.
Conclusion
Understanding the Norton Park sales policy can help buyers compare payment options, assess affordability and plan their finances more carefully. The standard, faster-payment and bank-supported approaches serve different needs, so the right choice depends on available capital, borrowing capacity and the buyer's long-term objectives.
Before proceeding, verify the latest price, payment milestones, incentives, legal documentation and handover terms for the specific apartment.
For further information about Norton Park apartments and other residential opportunities in the Ho Chi Minh City area, explore the property guides on Apartment for Rent and compare your options before making a decision.
Location
Tag
- Apartment for Rent
- Apartment for Sale in Ho Chi Minh City
- Gamuda Land Vietnam
- Ho Chi Minh City Real Estate
- Norton Park
- Norton Park apartment for sale
- Norton Park Bank Support
- Norton Park Discount
- Norton Park Gamuda Land
- Norton Park Gamuda Land price
- Norton Park Investment
- Norton Park Payment Plan
- Norton Park Payment Schedule
- Norton Park Price
- Norton Park Property Guide
- Norton Park Sales Policy
- Norton Park Sales Policy 2026
- property investment Vietnam
Review
Login to Write Your ReviewThere are no reviews yet.